Payee Data Record
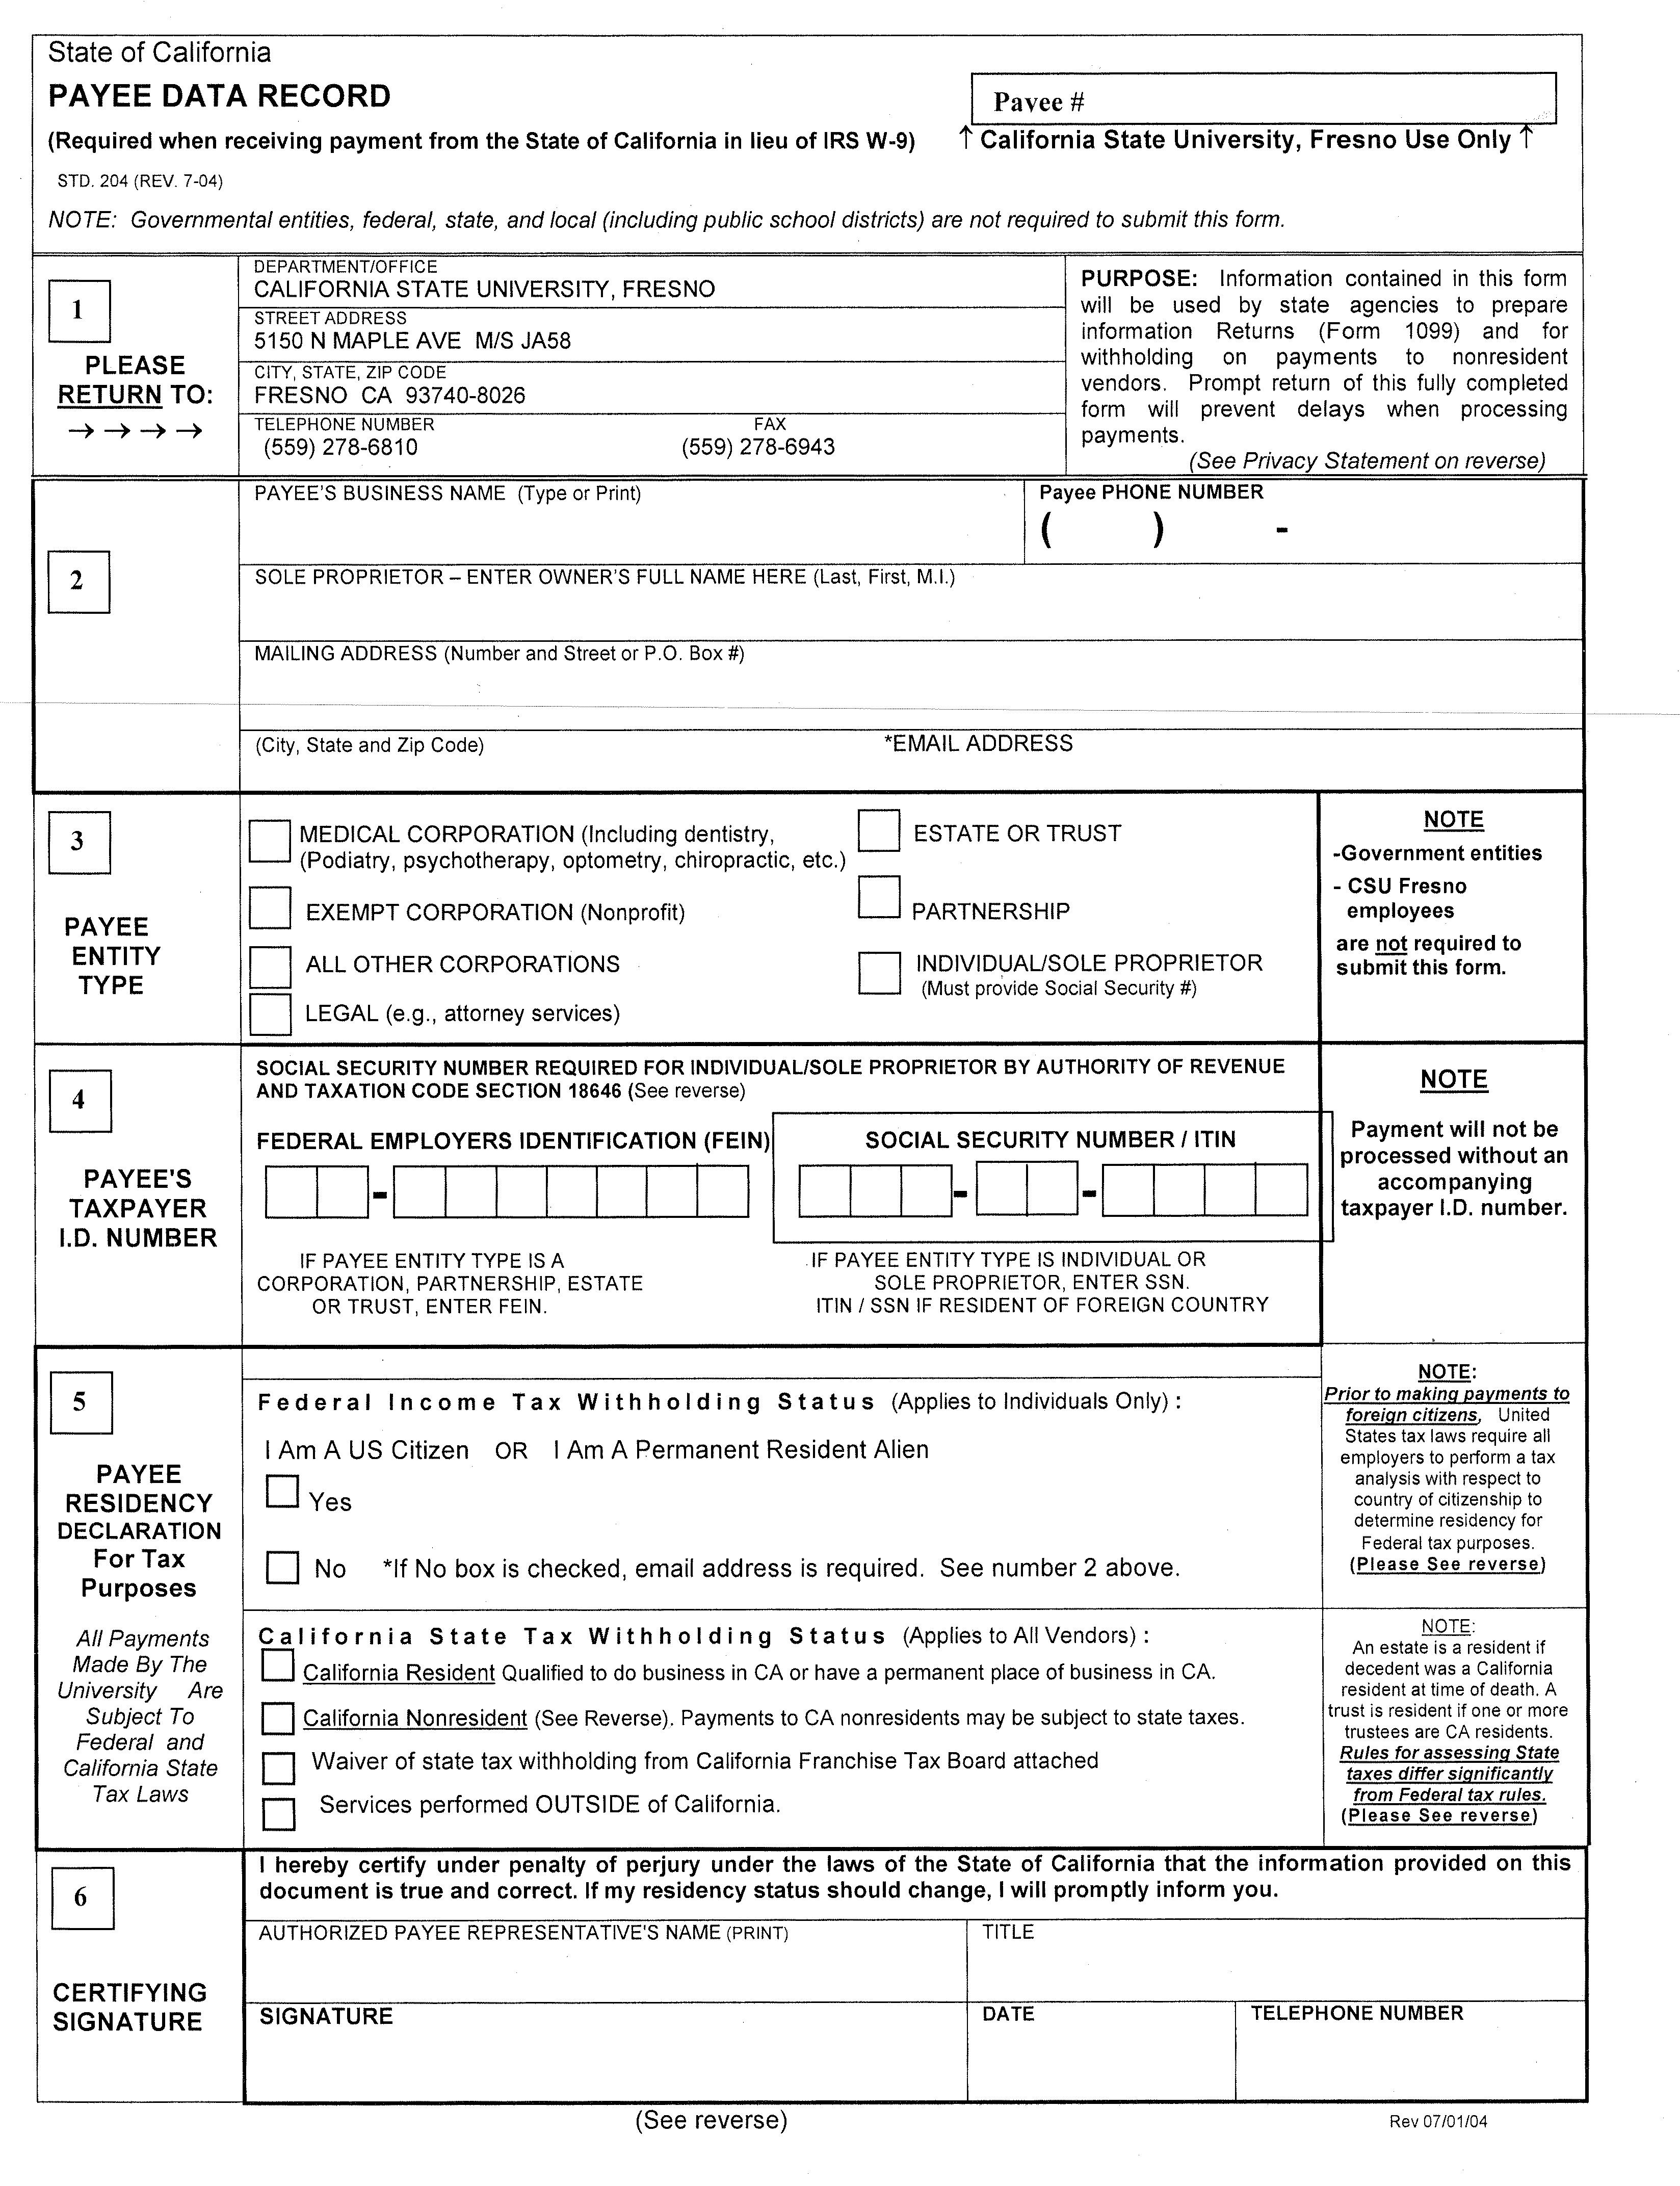
State of California
(Required when receiving payment from the State of California in lieu of IRS W-9)
STD. 204 (REV. 7-04)
NOTE: Governmental entities, federal, state, and local (including public school districts) are not required to submit this form.
Payee #
California State University, Fresno Use Only
1. PLEASE RETURN TO:
DEPARTMENT/OFFICE
CALIFORNIA STATE UNIVERSITY, FRESNO
STREET ADDRESS
5150 N MAPLE AVE M/S JA58
CITY, STATE, ZIP CODE
FRESNO CA 93740-8026
TELEPHONE NUMBER
(559) 278-6810
FAX
(559) 278-6943
PURPOSE: Information contained in this form will be used by state agencies to prepare information Returns (Form 1099) and for withholding on payments to nonresident vendors. Prompt return of this fully completed form will prevent delays when processing payments.
(See Privacy Statement on reverse)
2. PAYEE INFORMATION
PAYEE’S BUSINESS NAME (Type or Print)
Payee PHONE NUMBER
SOLE PROPRIETOR – ENTER OWNER’S FULL NAME HERE (Last, First, M.I.)
MAILING ADDRESS (Number and Street or P.O. Box #)
(City, State and Zip Code)
*EMAIL ADDRESS
3. PAYEE ENTITY TYPE
- MEDICAL CORPORATION (Including dentistry, (Podiatry, psychotherapy, optometry, chiropractic, etc.)
- EXEMPT CORPORATION (Nonprofit)
- ALL OTHER CORPORATIONS
- LEGAL (e.g., attorney services)
- ESTATE OR TRUST
- PARTNERSHIP
- INDIVIDUAL/SOLE PROPRIETOR (Must provide Social Security #)
NOTE
- Government entities
- CSU Fresno employees are not required to submit this form.
4. PAYEE’S TAXPAYER I.D. NUMBER
SOCIAL SECURITY NUMBER REQUIRED FOR INDIVIDUAL/SOLE PROPRIETOR BY AUTHORITY OF REVENUE AND TAXATION CODE SECTION 18646 (See reverse)
FEDERAL EMPLOYERS IDENTIFICATION (FEIN)
IF PAYEE ENTITY TYPE IS A CORPORATION, PARTNERSHIP, ESTATE OR TRUST, ENTER FEIN.
SOCIAL SECURITY NUMBER / ITIN
IF PAYEE ENTITY TYPE IS INDIVIDUAL OR SOLE PROPRIETOR, ENTER SSN.
ITIN / SSN IF RESIDENT OF FOREIGN COUNTRY
NOTE
Payment will not be processed without an accompanying taxpayer I.D. number.
5. PAYEE RESIDENCY DECLARATION For Tax Purposes
All Payments Made By The University Are Subject To Federal and California State Tax Laws
Federal Income Tax Withholding Status (Applies to Individuals Only):
I Am A US Citizen OR I Am A Permanent Resident Alien
- Yes
- No *If No box is checked, email address is required. See number 2 above.
NOTE: Prior to making payments to foreign citizens, United States tax laws require all employers to perform a tax analysis with respect to country of citizenship to determine residency for Federal tax purposes. (Please See reverse)
California State Tax Withholding Status (Applies to All Vendors):
- California Resident Qualified to do business in CA or have a permanent place of business in CA.
- California Nonresident (See Reverse). Payments to CA nonresidents may be subject to state taxes.
- Waiver of state tax withholding from California Franchise Tax Board attached
- Services performed OUTSIDE of California.
NOTE: An estate is a resident if decedent was a California resident at time of death. A trust is resident if one or more trustees are CA residents. Rules for assessing State taxes differ significantly from Federal tax rules. (Please See reverse)
6. CERTIFYING SIGNATURE
I hereby certify under penalty of perjury under the laws of the State of California that the information provided on this document is true and correct. If my residency status should change, I will promptly inform you.
AUTHORIZED PAYEE REPRESENTATIVE’S NAME (PRINT)
TITLE
SIGNATURE
DATE
TELEPHONE NUMBER
(See reverse)
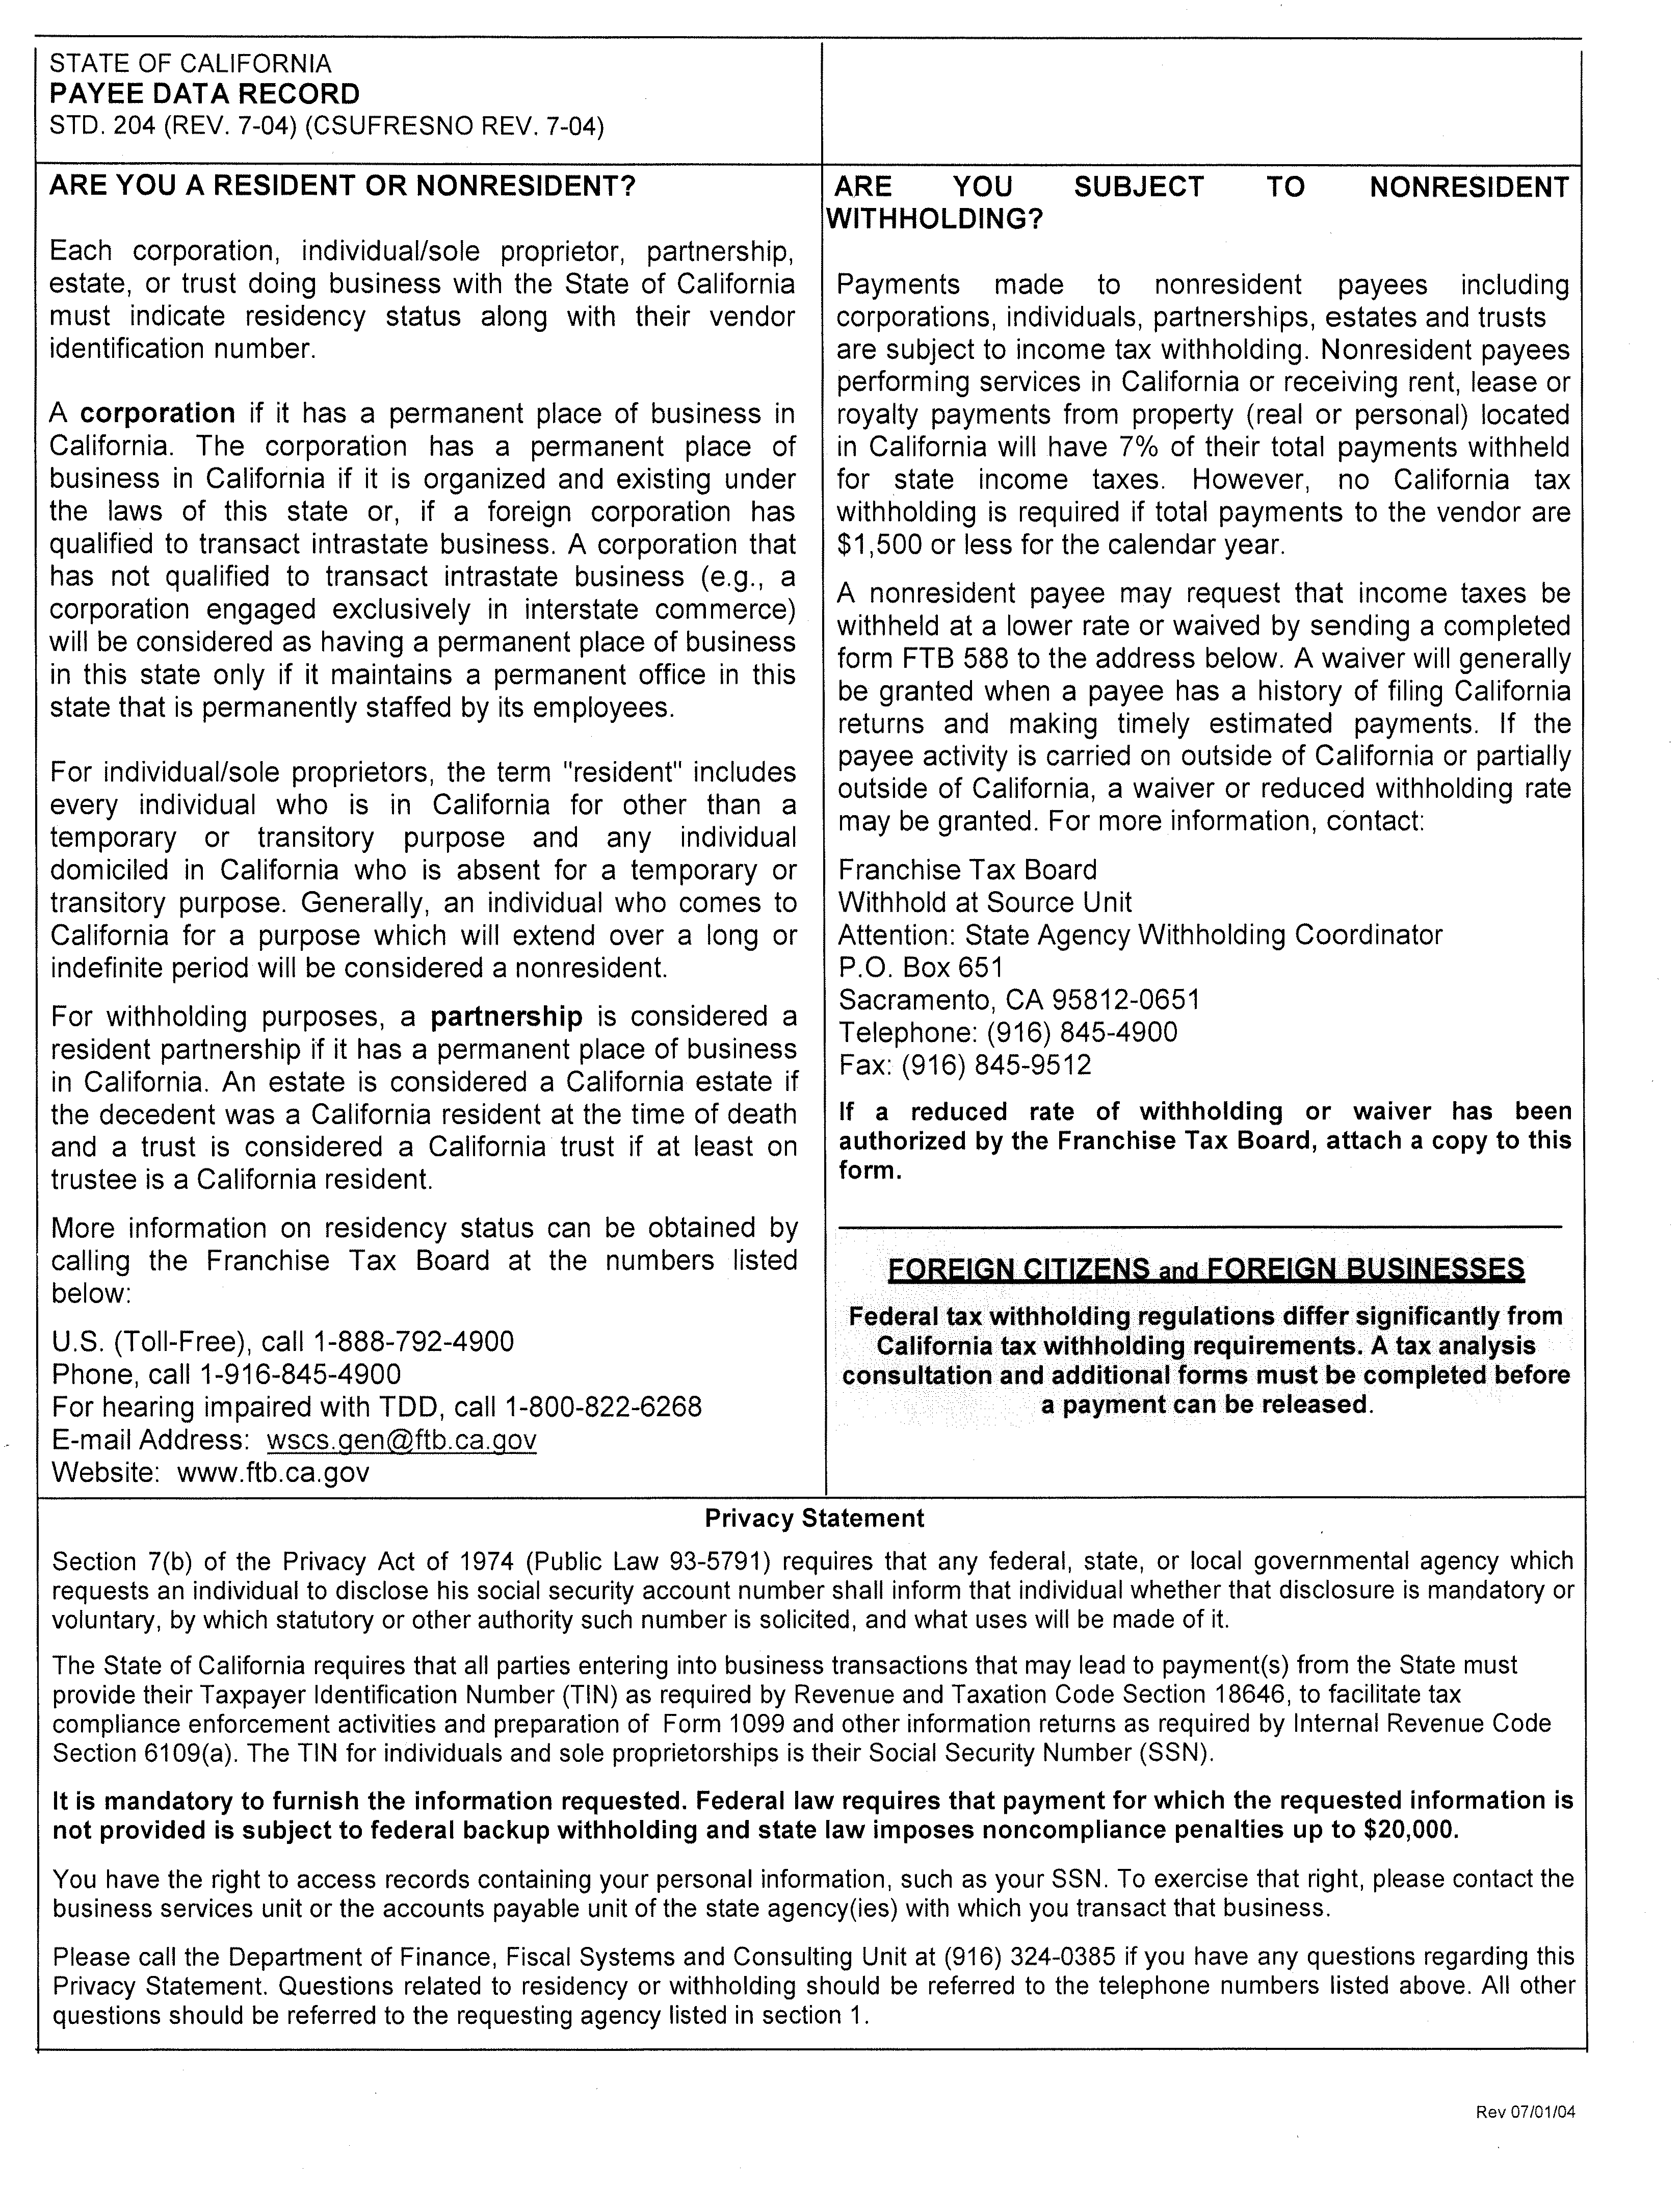
ARE YOU A RESIDENT OR NONRESIDENT?
Each corporation, individual/sole proprietor, partnership, estate, or trust doing business with the State of California must indicate residency status along with their vendor identification number.
A corporation if it has a permanent place of business in California. The corporation has a permanent place of business in California if it is organized and existing under the laws of this state or, if a foreign corporation has qualified to transact intrastate business. A corporation that has not qualified to transact intrastate business (e.g., a corporation engaged exclusively in interstate commerce) will be considered as having a permanent place of business in this state only if it maintains a permanent office in this state that is permanently staffed by its employees.
For individual/sole proprietors, the term “resident” includes every individual who is in California for other than a temporary or transitory purpose and any individual domiciled in California who is absent for a temporary or transitory purpose. Generally, an individual who comes to California for a purpose which will extend over a long or indefinite period will be considered a nonresident.
For withholding purposes, a partnership is considered a resident partnership if it has a permanent place of business in California. An estate is considered a California estate if the decedent was a California resident at the time of death and a trust is considered a California trust if at least one trustee is a California resident.
More information on residency status can be obtained by calling the Franchise Tax Board at the numbers listed below:
U.S. (Toll-Free), call 1-888-792-4900
Phone, call 1-916-845-4900
For hearing impaired with TDD, call 1-800-822-6268
E-mail Address: wscs.gen@ftb.ca.gov
Website: www.ftb.ca.gov
ARE YOU SUBJECT TO NONRESIDENT WITHHOLDING?
Payments made to nonresident payees including corporations, individuals, partnerships, estates and trusts are subject to income tax withholding. Nonresident payees performing services in California or receiving rent, lease or royalty payments from property (real or personal) located in California will have 7% of their total payments withheld for state income taxes. However, no California tax withholding is required if total payments to the vendor are $1,500 or less for the calendar year.
A nonresident payee may request that income taxes be withheld at a lower rate or waived by sending a completed form FTB 588 to the address below. A waiver will generally be granted when a payee has a history of filing California returns and making timely estimated payments. If the payee activity is carried on outside of California or partially outside of California, a waiver or reduced withholding rate may be granted. For more information, contact:
Franchise Tax Board
Withhold at Source Unit
Attention: State Agency Withholding Coordinator
P.O. Box 651
Sacramento, CA 95812-0651
Telephone: (916) 845-4900
Fax: (916) 845-9512
If a reduced rate of withholding or waiver has been authorized by the Franchise Tax Board, attach a copy to this form.
FOREIGN CITIZENS and FOREIGN BUSINESSES
Federal tax withholding regulations differ significantly from California tax withholding requirements. A tax analysis consultation and additional forms must be completed before a payment can be released.
Privacy Statement
Section 7(b) of the Privacy Act of 1974 (Public Law 93-5791) requires that any federal, state, or local governmental agency which requests an individual to disclose his social security account number shall inform that individual whether that disclosure is mandatory or voluntary, by which statutory or other authority such number is solicited, and what uses will be made of it.
The State of California requires that all parties entering into business transactions that may lead to payment(s) from the State must provide their Taxpayer Identification Number (TIN) as required by Revenue and Taxation Code Section 18646, to facilitate tax compliance enforcement activities and preparation of Form 1099 and other information returns as required by Internal Revenue Code Section 6109(a). The TIN for individuals and sole proprietorships is their Social Security Number (SSN).
It is mandatory to furnish the information requested. Federal law requires that payment for which the requested information is not provided is subject to federal backup withholding and state law imposes noncompliance penalties up to $20,000.
You have the right to access records containing your personal information, such as your SSN. To exercise that right, please contact the business services unit or the accounts payable unit of the state agency(ies) with which you transact that business.
Please call the Department of Finance, Fiscal Systems and Consulting Unit at (916) 324-0385 if you have any questions regarding this Privacy Statement. Questions related to residency or withholding should be referred to the telephone numbers listed above. All other questions should be referred to the requesting agency listed in section 1.
Rev 07/01/04
This PDF is provided as a print-only reference document and may not be fully accessible to users of assistive technology. For more information, please visit Title II Rule on Digital Accessibility page.